
How Nevada Insurers Use the 17c Formula to Minimize Diminished Value Claims
You file a diminished value claim after someone else wrecks your car. The insurer runs a formula. Your payout comes back at $200 or even zero. That number did not come from a Nevada law. It came from a formula that insurers choose because it works in their favor.
This article explains exactly how Nevada insurers use the 17c formula to minimize diminished-value claims, why Nevada law does not require them to use it, and which alternatives consistently produce higher recoveries.
Here is what you will find below. First, we explain where the 17c formula came from and how its structure is built to compress your payout. Then we walk through the math with a real-world example. After that, we cover what Nevada law actually requires and what it does not. Finally, we lay out your options: independent appraisal, legal challenge, and small claims court.
If your offer felt wrong, you were probably right.
Is the 17c Formula Required Under Nevada Law for Diminished Value Claims?
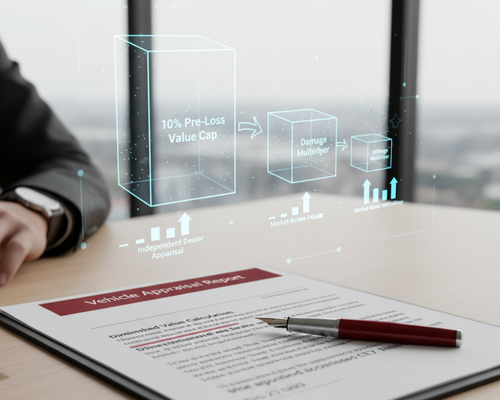
No. Nevada law does not require insurers to use the 17c formula to calculate diminished value. The formula was created by GEICO in the 1990s as an internal tool, not by any Nevada court or statute. Insurers use it because its built-in caps consistently produce payouts far below a vehicle’s actual market loss. The formula works in three steps: it caps your base loss at 10% of your car’s pre-loss value, then applies a damage multiplier, and then applies a mileage multiplier. Each step pushes the number lower. Nevada courts have accepted independent dealer appraisals and market-based methodologies as valid alternatives. If an insurer applied the 17c formula to your claim, that number is a starting point, not a legal verdict.
What Is the 17c Formula? Where It Came From and Why Insurers Love It
The 17c formula did not come from a Nevada statute or a Nevada court order. It traces back to a 2001 Georgia class-action case involving State Farm, in which the formula was created as an internal settlement tool. No Nevada law has ever adopted it. Insurers apply it by choice, not by legal obligation.
The formula works in three steps. First, it caps your base loss at 10% of your car’s pre-loss actual cash value (ACV). Second, it applies a damage multiplier between 0.00 and 1.00 based on the severity of your car’s damage. Third, it applies a mileage multiplier between 0.00 and 1.00 based on the number of miles on your odometer. Each multiplier further reduces the number.
That structure is the point. A vehicle with moderate damage and average mileage can end up with a 17c payout that is a small fraction of its real market loss. The formula looks like math. It is not neutral math.
Insurers use it consistently because it produces predictable, low numbers that are easy to defend. In our experience reviewing diminished value offers in Clark County, 17c results routinely come in 60–80% below what a licensed dealer appraisal produces. That gap is not a coincidence; it is built into the formula’s design.
Knowing where the formula came from is one thing. Seeing what it actually does to your payout number is another, and the math is not in your favor.
How the 17c Formula’s Built-In Caps Produce Near-Zero Payouts
Let’s use a real-world example. You own a 2021 Honda CR-V with a pre-loss actual cash value of $28,000. It suffered moderate structural damage in a crash on I-15. Your odometer reads 55,000 miles. Here is what the 17c formula does to your claim.
| Step | 17c Formula Result | Real-World Market Impact |
|---|---|---|
| Base loss (10% ACV cap) | $2,800 | A dealer may deduct $3,500–$5,000 at auction for accident history alone |
| Damage multiplier (moderate = 0.50) | $1,400 | Structural damage carries a heavier market stigma than the multiplier reflects |
| Mileage multiplier (55K miles = 0.40) | $560 | Mileage has no direct relationship to how much accident history hurts resale |
| Final 17c payout | ~$560 | Actual dealer trade-in loss: estimated $2,800–$4,500+ |
The 10% cap is the first hit. It limits your base loss to $2,800, regardless of the car’s actual market loss. The damage multiplier halves that. The mileage multiplier cuts it again. By the time the formula finishes, your $28,000 vehicle’s real-world loss has been reduced to a number that may not cover a single car payment.
What a licensed dealer or auto auction professional would actually deduct from that CR-V’s trade-in value has nothing to do with those multipliers. It is based on comparable sales, Carfax stigma, and current market conditions in the Las Vegas area. The 17c formula ignores all of that.
So the law doesn’t require this formula. The next question is: which methodology holds up in a Nevada court, and how do you get that number?
Is the 17c Formula the Legal Standard in Nevada? What the Law Actually Says
Nevada has no statute that requires insurers to use the 17c formula. A search of NRS Title 36 (Motor Vehicles) and NRS Chapter 687B (Insurance) finds no reference to the formula, no mandate to apply it, and no court order establishing it as the standard. Insurers use it because they choose to, not because Nevada law gives them cover.
What Nevada law does require is different. Nevada follows a “diminution in fair market value” standard for property damage claims. That means the at-fault party or their insurer owes you the actual difference between what your vehicle was worth before the crash and what it is worth after. A formula that caps and compresses that number through arbitrary multipliers does not satisfy that standard on its own.
Courts outside Nevada have also declined to treat the 17c formula as a binding legal benchmark. Its origin in a single Georgia case does not create precedential authority here. Nevada courts look at evidence of actual market loss, and that is where independent appraisals carry real weight.
In litigation, defense attorneys often point to the formula as a reasonable estimate. Plaintiff attorneys counter with licensed dealer testimony and comparable market data showing the actual loss the vehicle suffered. That contrast formula output versus real market evidence is exactly where these cases are decided.
Working with a Las Vegas diminished-value attorney means applying the right methodology to your claim from day one.
The Appraisal-Based Alternative: How Independent Experts Produce Higher, Court-Credible Numbers
An independent appraisal starts where the 17c formula stops. Instead of using a fixed multiplier structure, a licensed appraiser looks at actual comparable sales data. They measure what the same make, model, year, and condition sells for at wholesale and retail — before and after an accident history appears on the report. That difference is your real diminished value.
| Factor | 17c Formula Methodology | Independent Appraisal Methodology |
|---|---|---|
| Data source | Fixed multipliers (ACV cap, damage/mileage modifiers) | Comparable market sales, auction data, and Carfax impact analysis |
| Court credibility | Accepted as a starting point; not legally required | Accepted as evidence of actual loss in Nevada civil proceedings |
| Cost to obtain | None — insurer provides it free (and in their favor) | Typically $300–$600 for a certified appraisal report |
| Typical result | Fraction of real loss | Closer to the actual market diminution |
In the Las Vegas market, independent appraisal fees typically range from $300 to $600 for a certified report. For a vehicle with a pre-loss value of $30,000 or more, that fee is often recovered many times over in the increased recovery. The break-even math is straightforward: if your appraisal costs $500 and yields $3,500, compared with a 17c offer of $560, the report paid for itself several times over.
Luxury and exotic vehicles deserve special attention here. Las Vegas has a high concentration of Range Rovers, Mercedes, Teslas, and similar vehicles. These cars suffer disproportionate market loss after an accident. A buyer at a Las Vegas dealership or private sale will discount a luxury vehicle with accident history far more than the 17c mileage and damage multipliers account for. An independent appraiser who works in this market understands that gap and can document it in a format Nevada courts recognize.
Legal Arguments Nevada Attorneys Use to Challenge a 17c Offer in Court
If your insurer applied the 17c formula and you believe the result is unfair, Nevada law gives attorneys real tools to push back. Here are the four core arguments used to challenge a 17c offer in Clark County District Court.
1. The formula is not legally mandated in Nevada.
No NRS statute requires its use. The insurer chose it. That choice can be challenged, and the burden falls on the insurer to justify why a formula, rather than actual market evidence, satisfies Nevada’s diminution-in-fair-market-value standard.
2. The formula does not reflect actual market loss.
Nevada law requires compensation for the real difference in your vehicle’s market value before and after the accident. A 17c output compressed by arbitrary multipliers does not measure that. An independent appraisal does.
3. Systematic use of the formula may constitute bad faith under NRS 686A.310.
Nevada’s Unfair Claims Settlement Practices Act prohibits insurers from failing to pay fair value on valid claims. When an insurer consistently applies a self-serving formula that it knows produces results below the actual market loss, that pattern can support a bad-faith argument.
4. Independent appraiser and dealer testimony carries significant weight in Clark County.
Licensed appraisers and auto auction professionals who work in the Las Vegas market can testify to real comparable sales data. That testimony directly contradicts the formula’s output and provides a judge or jury with a market-based basis for a higher award.
In practice, we have seen clients come in with 17c offers as low as $400 on vehicles that independent appraisals valued at $3,800 or more in actual diminished value. Once the insurer understands that an attorney is prepared to bring market evidence and a bad-faith argument to the Clark County District Court, settlement discussions tend to move quickly.
Ready to push back? Call our Las Vegas office for a free case review.
Can You Fight a 17c Offer Without an Attorney? Small Claims Court in Nevada
Yes, but you need to go in prepared. Nevada’s Justice Court handles small claims up to $10,000 under NRS 73.010. You can file without an attorney. Clark County Justice Court filing fees for small claims are modest, typically under $100, depending on your claim amount. If your diminished value loss falls below the $10,000 threshold, small claims is a real option.
The practical challenge is proof. A judge is not going to accept your word over the insurer’s formula. You need documentation that establishes your vehicle’s actual market loss. Before you file, make sure you have the following:
- A written 17c offer from the insurer showing the formula output
- A certified independent appraisal report documenting actual diminished value
- Pre-loss ACV documentation (NADA, Kelley Blue Book, or dealer quote)
- Complete repair records showing the scope and cost of damage
- Your vehicle’s Carfax or accident history report
Without an independent appraisal, your small claims case is difficult to win. The insurer will send a staff representative who regularly handles these filings. They are practiced at defending the formula in court. Walking in without an appraisal report puts you at a serious disadvantage.
For claims above $10,000, which is common with luxury vehicles, trucks, or significant structural damage, small claims court is not available. Those cases belong in the Clark County District Court, where attorney representation is critical to building a market-evidence case that the insurer cannot easily dismiss.
Not sure whether small claims is the right move? Speak with a Nevada diminished value lawyer today.
Get A Consultation Today
Fill out the info below and we’ll give you a call.
