
How Diminished Value Is Calculated on a Luxury or Exotic Vehicle After a Las Vegas Accident
A Ferrari 488 retails for around $300,000. If it takes $18,000 in collision damage, you might expect to lose $5,000 or so in resale value. The real number is closer to $40,000, sometimes more. Yet the formula most Nevada insurers use treats that Ferrari the same as a Honda Accord. The result is a diminished value offer that doesn’t come close to your actual loss.
This article explains exactly how diminished value is calculated for a luxury or exotic vehicle after a Las Vegas accident, and why the default insurance formula was never designed for six-figure collectibles. You’ll see why standard multipliers fail exotic cars, what a certified appraisal actually looks at, what Nevada law lets you recover, and what to do if you’ve already received a lowball offer.
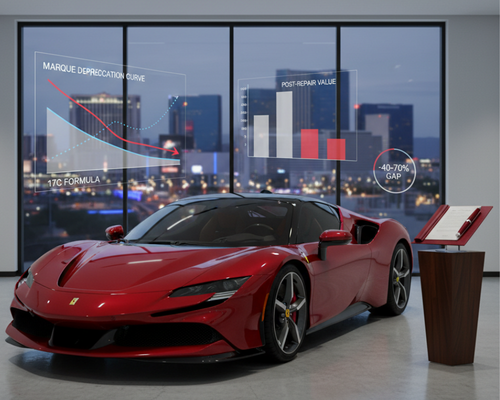
How is diminished value calculated on a luxury or exotic vehicle after a Las Vegas accident?
Diminished value on a luxury or exotic vehicle is calculated by comparing the car’s pre-accident fair market value to its post-repair market value. That gap reflects real losses — brand stigma, collector sensitivity to demand, and documented repair history. Nevada insurers typically apply the “17c formula,” which caps the base loss at 10% of the car’s actual cash value, then applies damage and mileage multipliers that further reduce the amount. On a Ferrari, Lamborghini, or high-end Mercedes, this formula routinely underestimates the actual market loss by 40–70%. Certified independent appraisers use brand-specific comparable sales, auction records, and marque depreciation curves — methods that reflect how exotic car buyers actually make purchasing decisions, not how insurers process mass-market claims.
Why the Standard 17c Diminished Value Formula Fails Exotic Cars
The 17c formula is the default method most Nevada insurers use to calculate diminished value. It starts with 10% of your car’s actual cash value (ACV). That number is then multiplied down using a damage multiplier (0.00–1.00) and a mileage multiplier (0.00–1.00). On a mass-market vehicle, this produces a rough approximation. On an exotic car, it produces a number that has little connection to real market loss.
Here’s the problem with the 10% ACV cap. On a $300,000 Ferrari, 10% gives you a $30,000 starting point. After the damage and mileage multipliers are applied, that number can drop to $3,000–$6,000. Meanwhile, the actual resale loss on that same car in the Las Vegas exotic market can exceed $40,000. The formula was built for high-volume passenger vehicles with deep resale comparables. Low-production exotics don’t fit that model.
The biggest gap the formula ignores is market stigma. Exotic and collector car buyers are far more sensitive to accident history than standard car buyers. A prior claim on a Lamborghini or high-end Mercedes doesn’t just reduce value slightly; it can eliminate entire buyer pools, disqualify the car from manufacturer-certified programs, and trigger higher insurance premiums for the next owner. None of that shows up in a 17c calculation.
| $300,000 Exotic | $45,000 Sedan | |
|---|---|---|
| 10% ACV Cap | $30,000 | $4,500 |
| After Damage Multiplier (0.25) | $7,500 | $1,125 |
| After Mileage Multiplier (0.50) | $3,750 | $562 |
| Realistic Market DV Loss | $40,000+ | $3,500–$5,000 |
Table figures are illustrative. Actual values depend on vehicle condition, repair scope, and current market data.
In our experience handling Ferrari and Lamborghini diminished value claims in Las Vegas, the 17c formula typically produces a figure that bears no relationship to what the car will actually sell for after a reported accident. That gap is documented, and it’s the foundation of every exotic DV dispute we take to an insurer.
How a Certified Appraiser Actually Calculates Exotic Vehicle Diminished Value
A certified independent appraiser doesn’t use a multiplier table. They look at what comparable vehicles are actually selling for, with and without accident history, using auction records, marque-specific depreciation curves, and OEM repair documentation. Two types of loss apply to exotic cars: inherent diminished value, which is the permanent stigma loss regardless of repair quality, and repair-related diminished value, which covers any loss tied to the work itself. Exotic buyers pay a premium for a clean history. That premium disappears the moment a claim hits the Carfax. A certified appraisal captures both losses. The 17c formula captures neither accurately.
Brand-specific factors matter more than most owners realize. Ferrari’s Classiche certification can be affected by non-OEM repairs. Lamborghini’s ad Personam customization adds value that standard depreciation models ignore. Rolls-Royce bespoke commissions create vehicles with no true comparable, making the 17c formula even less applicable. In Nevada DV disputes, a certified appraiser’s written report supports demand letters and, if needed, serves as expert witness testimony in litigation. That documented methodology is what separates a negotiable claim from one that an insurer dismisses with a form letter.
5 Factors a Certified Exotic Appraisal Examines That the 17c Formula Ignores
- Brand-specific comparable sales from active exotic and collector car markets
- Auction history and hammer prices for the same marque with and without accident history
- Manufacturer certification eligibility and whether the accident disqualifies the vehicle
- Marque-specific buyer pool behavior and accident-history aversion rates
- Bespoke, limited-edition, or personalization factors that affect the vehicle’s unique market value
When we retained an appraiser for a client’s exotic vehicle in Las Vegas, the certified report came back at more than three times the insurer’s 17c figure. That gap is what we bring to the negotiating table and what insurers have to answer for when they defend a formula-based offer against real market data.
Ready to fight your exotic car diminished value claim with a methodology that actually reflects your vehicle’s market value? Our team handles high-value DV disputes throughout the Las Vegas area.
What a Ferrari, Lamborghini, or Rolls-Royce Actually Loses After an Accident in Las Vegas
Exotic and collector car buyers behave differently from standard car buyers. They research accident history before making an offer. They know what a clean-title example sells for at Barrett-Jackson or Bring a Trailer. When they see a prior claim on a Carfax, they either walk away or discount aggressively. That behavior is predictable, and it translates directly into measurable resale loss that the 17c formula never accounts for.
The scale of that loss depends on the vehicle’s tier. On a $150,000 exotic, a significant accident history can reduce resale value by $15,000–$25,000. On a $250,000 vehicle, that range moves to $30,000–$50,000. At the $400,000+ level, think Rolls-Royce Cullinan or a low-production Ferrari, the loss can exceed $70,000. These are market-driven figures, not formula outputs. They reflect what buyers in the Las Vegas exotic market actually pay for accident-free examples versus cars with a reported claim.
| Vehicle Tier | Est. Pre-Accident Value | Typical 17c Output | Realistic Market DV Loss |
|---|---|---|---|
| Entry Exotic | $150,000 | $3,000–$6,000 | $15,000–$25,000 |
| Mid-Tier Exotic | $250,000 | $5,000–$9,000 | $30,000–$50,000 |
| Ultra-High-End | $400,000+ | $8,000–$14,000 | $70,000+ |
Figures are illustrative estimates based on general market behavior. Actual DV loss depends on vehicle condition, repair scope, and current market data. Independent appraisal required for claim purposes.
Las Vegas is not a typical resale market. The city has a high concentration of exotic-vehicle inventory, ranging from dealerships like Gaudin Ferrari and Towbin Motorcars to private collectors and Strip-adjacent buyers. That buyer pool is sophisticated. They know disclosure rules. They factor accident history into offers with precision. A prior claim on your vehicle doesn’t just affect what a private buyer pays; it can affect auction eligibility, future collector certification, and what your insurer charges the next owner to cover the car.
Nevada Law and Your Right to Full Diminished Value Recovery
Nevada law recognizes inherent diminished value as a recoverable damage in third-party claims against an at-fault driver’s insurer. That means if another driver caused your accident, you have the right to pursue the full market loss your exotic vehicle sustained, not just repair costs. First-party claims, filed against your own insurer, are a different matter. Nevada does not require first-party DV coverage unless your policy specifically includes it. For most exotic car owners, the primary recovery path runs through the at-fault driver’s liability coverage.
If you were partially at fault, Nevada’s modified comparative negligence rule under NRS 41.141 still allows you to recover — as long as your share of fault is below 51%. Your DV recovery is reduced proportionally by your fault percentage. On a $50,000 exotic car DV claim, even a 20% fault finding reduces your recovery by $10,000. That’s why fault allocation matters as much as the appraisal number on a high-value claim.
Time is also a factor. Under NRS 11.190(4)(e), you have two years from the date of the accident to file a property damage claim in Nevada. That window sounds generous. It isn’t — not for exotic cars. Appraisal quality depends on the preservation of the vehicle’s post-repair condition and documentation. The longer you wait, the harder it becomes to establish a clean baseline for your pre-accident value. If your insurer is stalling, that delay works in their favor.
When an insurer repeatedly lowballs a legitimate exotic car claim or denies it without basis, Nevada’s unfair claims practices act applies.
When an insurer repeatedly lowballs a legitimate exotic car claim or denies it without basis, Nevada’s unfair claims practices act applies. Under NRS 686A.310, insurers are prohibited from failing to acknowledge claims, misrepresenting policy terms, or refusing to pay valid claims without conducting a reasonable investigation. Bad faith exposure is a meaningful lever — and attorney involvement makes that exposure real to the insurer in a way that a demand letter alone often doesn’t.
4 Nevada Legal Facts Every Exotic Car Owner Must Know Before Settling a DV Claim
- Nevada recognizes inherent diminished value as a recoverable third-party tort damage — you are entitled to pursue the full market loss, not just repair costs.
- NRS 41.141 limits recovery if you were 51% or more at fault — but partial fault below that threshold still allows proportional recovery
- NRS 11.190(4)(e) gives you two years from the accident date to file — waiting reduces appraisal quality and documentation strength
- NRS 686A.310 exposes insurers to bad faith liability when they repeatedly lowball or deny valid DV claims without reasonable investigation
If your insurer’s offer doesn’t reflect what your vehicle has actually lost, call our Las Vegas office for a free case review.
What to Do If the Insurance Adjuster’s Offer Is Too Low: Step-by-Step
Insurers count on exotic car owners to accept the first offer. The 17c formula produces a number quickly, and adjusters present it with confidence. But a fast offer is not a fair offer, especially on a Ferrari, Lamborghini, or high-end Mercedes, where the real market loss can be ten times what the formula produces. Here’s exactly what to do if the number you’ve received doesn’t reflect your vehicle’s actual loss.
Step 1: Do not accept the offer yet.
Verbal or written acceptance typically closes the claim. Before you respond, get the insurer’s offer documented in writing. Note the date, the adjuster’s name, and the exact figure. That record becomes the foundation of your dispute.
Step 2: Get a certified independent appraisal immediately.
Preserve your vehicle in its post-repair condition for the appraiser’s inspection. Photograph everything: every panel, every repair receipt, every OEM part sticker. The appraiser needs a clean baseline to establish the pre-accident value and document the gap.
Step 3: Request the insurer’s methodology in writing.
Ask specifically which formula was used, what ACV figure they applied, and which damage and mileage multipliers were selected. Most adjusters won’t volunteer this. Putting the request in writing creates a paper trail that supports negotiation or litigation.
Step 4: Compare the two appraisals and identify the gap.
If the certified appraisal exceeds the insurer’s figure by $10,000 or more, a demand letter supported by appraiser testimony is your next move. That letter puts the insurer on notice and exposes it to bad-faith liability under NRS 686A.310 if it continues to stonewall.
Step 5: Consult a Las Vegas diminished value lawyer.
Attorney involvement changes the insurer’s calculus. Bad faith exposure under NRS 686A.310 becomes a real litigation risk when a lawyer enters the picture. Insurers who ignore demand letters from owners often respond very differently when they’re looking at a filed complaint.
Clients often come to us after already accepting a DV check. In most cases, that acceptance is binding. Don’t let the insurer’s timeline pressure you into closing a $40,000 gap for $4,000. The time to act is before you sign anything.
Don’t let the insurer’s formula decide what your Ferrari, Lamborghini, or high-end Mercedes is worth. Call our Las Vegas office for a free case review · Get directions to our Las Vegas office· Learn more about diminished value claims in Las Vegas.
Get A Consultation Today
Fill out the info below and we’ll give you a call.
